INDIA-AMERICA-BRITISH

WELCOME TO KATY INDIA- ALL THE ARTICLES WRITTEN BY LOKANATH MISHRA ON INDIAN-AMERICAN -BRITISH - SOCIAL AND CULTURAL MATTERS ARE BEING RE PRODUCED IN THIS BLOG POST
LORD SHRI JAGANNATH & LORD SHRI KRISHNA ARE MAHA VISHNU.SHRI JAGANNATH IS BEING WORSHIPED THROUGHOUT THE WORLD.

Saturday, 28 July 2018

DRI busts multi-crore imported garment smuggling racket; 

Kolkata, Jul 26 (PTI) A syndicate that smuggled undervalued and mis-declared readymade garments from China and Hong Kong SAR into India has been busted with the arrest of four people, the DRI said today.

The accused were part of a Kolkata-based syndicate operating through different ports in the country and involved in importing goods valued at over Rs 130 crore by under-valuing the price and evading customs duty of at least Rs 25 crore, a statement issued by the agency said.

Giving details, the Directorate of Revenue Intelligence (DRI) said a consignment imported by a local firm was examined.

"On examination, mis-declared items such as ladies fancy top, girls fancy night wear, fancy swim wear, ladies waist accessories etc, in commercial quantities were found against declared items like girls slips, ladies stocking, girls night dress, washing bag etc, valued at Rs 4.62 crore against the declared value of Rs 35 lakh, and subsequently seized," it said.

The firm is part of the syndicate engaged in mis-declared imports through the Kolkata and Haldia ports. Four other firms are also part of this illegal activity.

The DRI also intercepted another mis-declared consignment of ready made garments imported by the syndicate in the name of one of these firms.

The goods were found to be mis-declared in terms of description, value and quantity.

Upon examination, the value was found to be Rs 6.62 crore against the declared value of Rs 36 lakh, the DRI said.

Three other consignments of three different firms of the syndicate were also intercepted and examined, and found to be mis-declared in terms of description, value and quantity.

"Thus, a total of five live consignments pertaining to the syndicate, having total market value of about Rs 20 crore against the total declared value of Rs 1.5 crore, have been seized," it said.

The DRI said a follow-up inquiry was conducted in Mumbai at certain premises, owned by one of the accused.

The officials found Rs 77 lakh from these premises, which admittedly was the sale proceeds of such mis-declared goods, which were seized, the agency said.

Besides cash, original invoices revealing the correct and much higher values of 86 consignments imported in the past by the syndicate with respect to the five companies were also recovered.

The accused have admitted that they were involved in the fraudulent import of mis-declared goods in respect of 130 consignments, the differential value of which is more than Rs 100 crore and which involves evasion of customs duty of about Rs 25 crore, the probe agency said.

The DRI said another 132 consignments have been imported in the past by the syndicate using the same modus operandi and it has evaded huge customs duty. "Thus, the total evasion of customs duty by the syndicate could be much higher than Rs 25 crore," it said.

Detection of this modus operandi will not only discourage cheap and fraudulent imports by unscrupulous traders, but will protect domestic readymade garment manufacturers, especially small and medium sector enterprises which form the backbone of the textile industry, the DRI said. PTI AKV AKV ANB ANB
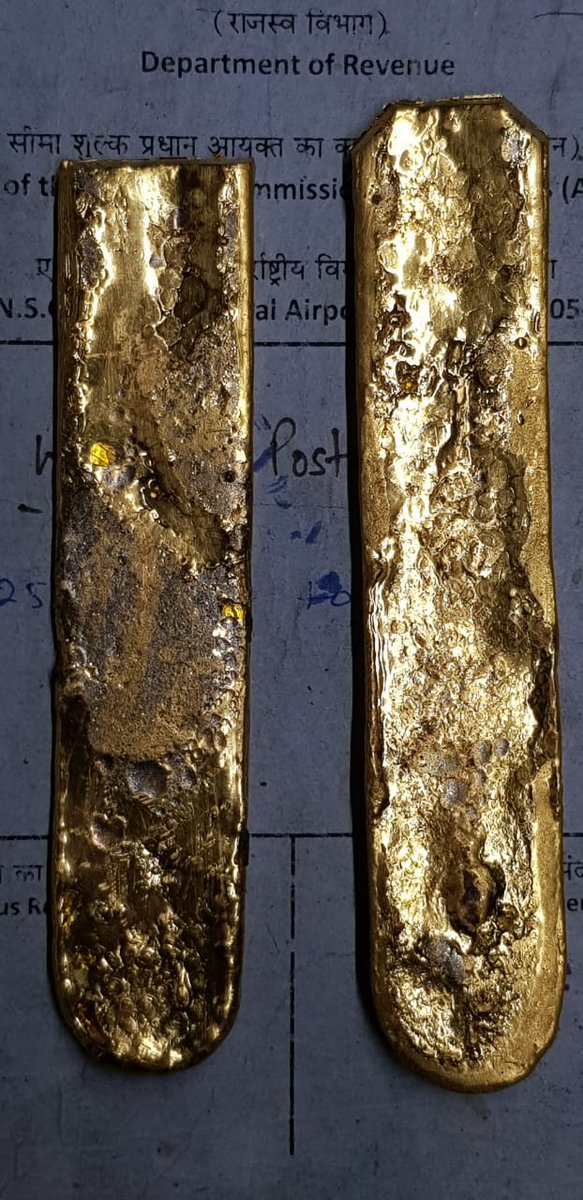
  1. The AIU, Kolkata seized 970 grams of gold valued at Rs.29,48,800/- from a Pax arrived from Dubai by EK 570 on 26.07.2018. In a unique modus operandi gold was mixed with health supplements in dust form. The pax has been arrested and further investigation is under process.
     

Effective date of MACP is 01.01.2006. Govt has implemented the decision of Apex Court in case of Army personnel.

Effective date of MACPS for Army

Wednesday, 25 July 2018

-Lessons Learnt from the Implementation of Cadre Restructuring in CBEC 2013 -

 Research Paper

 Change is indispensable part of everyone’s life. In fact, change is the only thing that is eternal in the universe in all senses. Change occurs everywhere, everyday and in everyone and organizations are no exceptions. Organisational changes invariably involve one or the more of the following namely, processes, systems, Organization Structure, and job roles (Creasy, 2007). While project management deals with accomplishment through the application and integration of the project management processes of initiating, planning, executing, monitoring and controlling, and closing, change management incorporates the organizational tools that can be utilized to help individuals make successful personal transitions resulting in the adoption and realization of change(Creasy, 2007). The Central Board of Excise and Customs (CBEC) underwent a massive restructuring wherein the number of formations at the field increased; new functional units were created; and created promotional opportunities to many in the entire hierarchy. One of the major objectives of this cadre restructuring was to have an effective compliance monitoring mechanism by creating units with smaller jurisdictions and also functional specialization such as audit. According to CBEC, cadre restructuring involves devising a holistic manpower management plan and reorganization of field formations on scientific basis to improve productivity and quality of deliverables. It is also a mean to align human resource architecture with business process strategy to ensure that there is smooth change management and effective implementation of strategic goals of the department. While on one side it aims at enhancing core competencies, on the other hand tries to satisfy the stakeholders in facilitating honest tax payers as well as creating deterrence against tax evaders (CBEC, 2010). Thus Cadre restructuring itself is a part of change management in the indirect tax administration in India. No doubt, there are more field formations, more promotional avenues and more opportunities for specialization in each area of indirect taxation. However, whether the recent cadre restructuring in CBEC takes along the principles of change management in a holistic manner so that it meets the objectives effectively is a question that remains unresolved. This paper attempts to address the above question by deliberating the principles of change management and comparing the world models by studying the similar exercises undertaken in other countries and the experiences learnt therein. The first part will deal with the theoretical basis of change management. The second part will discuss on the background and scheme of cadre restructuring in Government of India and CBEC. The international experiences will be discussed in part three of the paper and the concluding part will give suggestions on how to move forward. Change and management of change Change happens at various fronts- the way we think, communicate, act or create new relationships and structures in an organization to redefine in response to the changes happening in the environment. Change is cahrectersied as crystallization of new actions and possibilities on reconeptualised patterns of organization as well as redefining the architecture of Organisational structure. (Felkins, Cakiris, & Chakiris, 1993). Change may be directed from top down or itcan be a continuous non directed process (ibid). Change can originate from external sources through technological advances, social, political or economic pressures, or it can come from inside the Organisation as a management response to a range of issues such as changing client needs, costs or a human resource or a performance issue. It can affect one small area or the entire Organisation. Nevertheless, all change whether from internal or external sources, large or small, involves adopting new mindsets, processes, policies, practices and behavior. Invariably all changes have the following characteristics namely, - it involves contradictions, it is a continuous process, it is interpreted through the perceptions and interactions of the people and facilitated through collaborative inquiry and team work (ibid). Leavitt observed that Organisational change can impact four variables-task or the purpose for which the organization exists, competencies of the people, the process or the technology by which the task is accomplished and structure involving communication, power, reporting systems (Paton & McCalman, 2013). In CBEC, changes are happening continually and they impacted to a great extent the task we perform. We are no longer mere regulators or enforcers of law; in the past two decades our role has gradually changed to a facilitator. Certain changes impacted the process also. Introduction of ICES, ACES, ICEGATE, RMS and IT Consolidation project changed the way we perform our work. Various capacity building programmes in different areas such as IT skills, Risk Management, EA 2000 etc no doubt impacted the competencies of the people working in the organization. And periodical cadre restructuring changes the structure as well as the functions of the formation. In all the change processes the broad objective is improving the efficiency and effectiveness. Though there is no empirical studies available it cannot be an overstatement to say that the structural change brought in the 2002 cadre restructuring has improved efficiency in terms of compliance monitoring and plugging avoidance and evasion of duties and taxes through well monitored scrutiny, audit and antievasion works. While there are numerous models of change management, no single approach suits all planned change. It is important that the change approach adopted is one that is suited to the culture of the organisation and the context of the change. While each public sector organisation needs to consider the best way to approach change, there are common change management principles that characterise successful change. The extent to which those principles are exhibited will vary, depending on the extent and nature of the change. The principles for managing successful structural change are: A clearly defined rationale and vision of the change is understood; stakeholders are identified, appropriately consulted and informed; The system and processes developed to achieve the change are transparent; Collective and collaborative leadership is empowered; There is a dedicated focus on peopleand the change is systematically reviewed and adapted(Workforce performance Directrate, 2015). No single process is suitable for all structural change. However, there are some common interlocking process steps that should be followed. The process is not typically linear; the steps interlock and merge, allowing one step to begin prior to another being completed. The steps comprise design, deliver, dialogue, do Change management: Challenges All changes are required to be implemented as part of a strategy to accomplish an overall goal; these transformations should not take place just for the sake of change.It is quite rare that restructuring plan of any organization go smoothly and not met with any opposition or resistance. Quite a few times, this opposition is because of real threats, but many a times these threat perceptions are unfounded one and not on strong footing. History shows that workers have resisted some of the best‐laid plans. A few may openly fight it. Many more may ignore or try to sabotage a plan. In today’s business world, most people, most of the time, resist change. These people believe that change is rarely for the better. They believe that fruits of the restructuring will be eaten up by the top few and they will be left with very meager benefits. For this category of individuals, at the end of the day, the whole exercise seems like a waste of time. Threat of retrenchment or longer working hours and lessening of promotional avenues for some cadres also strengthen the resistance amongst the lower staff. These kinds of dismal scenarios give employees the impression that change is not good. And employees have no reason to believe that it's going to be better in the future. A number of the most common reasons for which employees resist change are:  Uncertainty and insecurity  Reaction against the way change is presented  Threats to vested interests  Cynicism and lack of trust  Perceptual differences and lack of understanding In order to overcome resistance, broader consultations is necessary with all stakeholders whose interests are affected by the change process by communicating openly about changes, providing advance notice of an upcoming change, exercising sensitivity to concerns of field officers, and reassuring field officers that change will not affect their security. In addition, successful implementation of changes may be ensured if some common pitfalls are avoided that cause changes to fail. The same are as follows:  Faulty thinking  Inadequate change process  Insufficient resources  Lack of commitment to change  Poor timing  A culture resistant to change(Cliffs Notes) Tax administration: changes around the world A tax administration should define its own objectives and performance horizon within an agreed framework. It should also carry the full responsibility of formulating its own strategies and operational plans so that it can respond rapidly to the changing circumstances resulting from increasing globalization represented by emerging business arrangements and the corresponding needs of the tax administration. Some of the traditional views or structures need reorientation and change. The preoccupation of “how” to administer has to yield to “why” and “for what”. It is for these reasons that modernizing a tax administration changes the existing organizational structure to fit the needs of the time, reorganizing its activities in an effective and efficient way. This could include decisions on the number, size and geographical location of tax offices. In the past two decades, world over the tax administrations underwent changes with a view to enhance efficiency and effectiveness (TARC, 2014). These reforms were in response to demands for extensive and deeper information, not only form the respective governments but from the governments elsewhere. Taxpayers also demand better and more economical and effective tax services. Changing paradigms like trust based clearance and self-assessment, risk based selective audit, and other non-adversarial approach for tax collection, need structural changes as well. The OECD report on tax administrations found that reforms around the world have moved along two main axes –(a) revamping institutional mechanisms for governance and (b) reorganizing the machinery for tax administration. The first one addresses the organizational structures and processes for tax governance focused on outcomes, with an emphasis on improvements in the efficiency and effectiveness of operations. They have moved from tax- type organizational structures to staff being organized along functional groupings. This approach permits better management of and better outcomes from core functions and greater consistency and coherence in the administration’s interface with taxpayers. It has permitted better standardization and greater operational efficiency leading to improved organizational performance and productivity. Alongside functional restructuring, the approach also segments taxpayers in order to better target administration policies, services and compliance management activities in reflection of taxpayer needs and behaviors. The OECD survey indicates that 49 out of the 52 surveyed countries had “function” as a key element in their organizational structure (OECD, 2013). Several tax administrations are undergoing major organizational reform to achieve improved outcomes, in particular in areas such as increasing application of customer segmentation approaches (including large taxpayer units), bringing separate verticals for more focused delivery and on expanding the ICT base. (OECD, 2013) CBEC Cadre Restructuring Background Indirect Taxe governance and administration witnessed many pages of the law being changed and re-written quite a few times. Many redundant and obsolete practices have fallen by the way side and in their place rose a more lean and transparent code that signifies a dynamic response to change. The Central Board of Excise and Customs implemented changes with an unwavering focus on efficacious service delivery and tangible transparency in dealings. The Department has evolved into an efficient tax administration system by adapting itself to the challenges of the changing economic scenario, technological advancements and the liberalization process taking place all over the world. From the role of a controller and enforcer, the Department has emerged as the facilitator. The change management has been done in a seamless way and we have bound ourselves in the spirit of the Citizens Charter and pledged to make it a reality, rather than a mere rhetoric. The significant milestones of the Department in the journey towards building of an effective Tax Administration System for a stronger Nation are as follows: 1944: All the Excise Acts were consolidated into a single Central Excise Act. 1962: The Customs Act came into being replacing assorted Acts that goverened Customs at Sea, Land and Airports. 1963: Board of Revenue Act came into being wereby the CBEC has come into existance to adminster the indirect Taxes in the Country namely the Central Excise Act 1944 and the Customs Act 1962. 1969: Self Removal Procedure was introduced replacing physical control signaling the change of attitude of the Department towards the assessees. 1975: Customs Tarif hormaonised with the rest of theworld. 1978: Record Based Control was introduced on certain commodities as a further measure of liberalization. 1986: MODVAT scheme (presently known as CENVAT) was introduced to facilitate the manufacturers to set off the duty paid on the inputs and capital goods against the duty payable on the final products. 1994: Service Tax, the new concept of levying tax on services was introduced with an initial coverage of 3 services with a potential to have magnificent growth to cover more than 100 services in future. 1996: "Self Assessment Procedure" and “SelectiveAudit” were introduced which vested total freedom and trust in the assessees. 1996: ICES was introduced in Customs heralding in ICT based tax administration. 2000: Exise Audit-2000 was introduced. Consignment based payment of duty was replaced by fortnightly payment. 2001 and 2002 : New set of Central Excise Rules were introduced. THe Central excise rules were redeuced in number from more than 250 rules to just 30 plus rules. 2002: Onlline registration of Cnetral Excise and Service Tax Asssessees was introduced. 2003: ICEGATE was created for online processing of customs clearances. 2003: The restrictions on the movement of excisable goods on the Budget day were removed. Fortnightly payment of duty was replaced by monthly payment of duty. 2004: Cenvat Credit Rules, 2004 were introduced to facilitate both manufacturers and service providers for availment of Cenvat credit of duty/tax paid on the inputs, input services and Capital goods. 2006: Risk Management System was put inplace in Customs whereby the import documents were assessed on selective basis. 2009: ACES was introduced in Central Excise and Service Tax. 2012: Service Tax revamped with the intruduction of negative list barring wich all services were made taxable. Restructuring In accordance with the need to synchronize with the policy decisions of the Government, the Department undertakes various innovative initiatives periodically to serve the trade and industry. One of such major preiodical initiatives is cadre restructuring. It helps to prepare and equip the Officers to face the challenges of the constant changes and developments around the Department; it aids in re-organization of the formations at all levels;it also aims at enhancing the efficiency of the department for achieving the goals in an effective manner for the betterment of the Nation as well as the Trade and Industry. In the past the major cadre restructuring exercises were undertaken in 1971, 1983, 1997 and 2002. The re-structuring and re-organization of the formations of the Department, which took place in the year 2002, was based on the statistical data and economic environment prevalent in the year 2000. To meet the challenges as existed then, smaller Zones and Commissionerates were created which has taken the services at the cutting edges of the Department closer to the locations of the Trade and Industry. In order to ensure speedy disposal of Appeals, more formations of Commissioners (Appeals) were created. These measures, as the data available clearly indicate, proved to be result oriented providing a win-win situation both for the Department as well as the Trade and Industry(Study Group I, 2010)(Study Group II, 2010). The Change Process –Design The department is not an isolated entity immune from external and internal stimuli. The proactive and responsive Tax Administration that it is, the Central Board of Excise and Customs has initiated the process of responding to the changed economic scenario and other poignant stimulus by initiating a Cadre Reorganization and Restructuring of the field formations. The recent exercise of cadre re-structuring and re-organization of the formations is significant, as the challenges ahead of us are tough. The Global economic meltdown and its cascading effect on all Nations was clear and profound. The effect of recession in countries having close and significant economic ties with India needed an imaginative response. The slowdown in the manufacturing sector and sluggish Exports are alarming. Against these odds, we had the proud task of moving forward to elevate the Nation to greater heights with the Vision that India will be one of the super powers of the World by 2020. Constitution of Study Groups The Central Board of Excise and Customs had constituted three Study Groups for undertaking the exercise relating to cadre restructuring/ reorganization of the field formations of the CBEC in 2008. The Study groups conducted detailed study on various aspects includingRevenue scenario, work load at all levels, projected work load at all levels,numbers of assessee, export/imports, bills filed, refunds, rebates, adjudicationand appeals, anti-evasion measures, anti-smuggling activities, number of workforce available, infra structure, administrative requirements as per terms ofreference and submitted their final reports to the Board recommending re-structuing of field formations and various cadre for effective administration andTax collection.  The service sector in India has been the sunrise area of taxation since the last cadre review and has shown phenomenal growth since inception, last six years in particular. There was an urgent need to provide additional manpower in this area to tap the vast potential.  Service Tax was being managed under great constraints of manpower. Its total collections are already equal to the non-POL Central Excise revenue, whereas the total workforce was only a very small fraction of the manpower deployed in Central Excise.  In Cnetral Excise, the new Commissionerates are proposed on the twin criteria of revenue collection as well as workload in terms of the number of units. Change Process- Deliver  It was recommended to create exclusive Central Excise Commissionerates on the norm of 1500 assessees and revenue in the range of Rs.1500 crore to Rs.2000 crore. Each Commissionerate may have five Divisions with six Ranges each. Overall staff strength of a Commissionerate is recommended as 428.  There were clear trends in manufacturing activity moving away from major cities, which are centres of Service Tax collections. As a result the Central Excise revenue is largely stagnant in these cities or at least not growing at the pace witnessed in other taxes. Accordingly the number of Commissinerates in Mumbai are being reduced from the existing 8 to 6 and in Kolkatta from 7 to 5. However there has been noticeable growth in some regions. As a result two new Commissionerates are being proposed in Delhi Zone- one each at Gurgaon and Faridabd by bifurcating the existing Commissionerates- and one at Bangalore  Consequent upon creation of exclusive Service Tax Commissionerates at new locations the existing Central Excise Commissionerates in the respective jurisdictions of Hyderabad, Pune, Rajkot, Jaipur, Ghaziabad and Noida will become ii exclusive or may have very little revenue from Service Tax in some far flung areas.  Creation of two additional posts of Chief Commissioners at Delhi and GhaziabadNoida is also recommended.  The recommendations have been made keeping in view the present regime of tax collections, with due allowances for foreseeable changes.  The advent of GST, expected to be introduced from April, 2010 to have major impact on the way many of the processes are carried. In fact much of the distinction between goods and services will vanish and to that extent the concept of exclusive Service Tax and exclusive Central Excise Commissionerates may need to be revisited.  While this switchover may take some time, it was necessary that the Department should position itself in a very high level of preparedness to meet the new challenge, particularly in the area of Service Tax, by implementing the review before the GST is brought into force.  The taxpayer participation in LTUs at Bangalore, Chennai, Mumbai and Delhi has registered positive growth and the feed back obtained from the large taxpayers indicated high satisfaction levels. Compliance improvement in the form of improved recoveries through audit/ anti-evasion etc., also pointed to the benefits that will accrue to the department in the long run due to focused approach on large business entities who account for substantial tax revenues to the government. The existing system of posting officers and staff on ad-hoc basis needs urgent review. Though the entry into and exit from the scheme was optional, it is worth noting that none of the large taxpayers have opted out of the scheme from any of the LTUs in the last two and half years which clearly indicated that the scheme has come to stay and will be continued. If adequate number of officers are not posted in LTUs, the risk to revenue cannot be ruled out especially when eligibility criteria applicable at present do not distinguish a large taxpayer whether compliant or not as is being followed in RMS in the Customs side. The staff compliment suggested above takes into account the norms suggested in the Approach Paper, the report submitted by the Human Resource Group constituted by CBECand CBDT and the working experience gained in the last two and half years, particularly at Bangalore and Chennai. Suitable adjustments in the staffing requirement has been suggested in this paper, compared to the suggestion contained in the aforementioned reports in view of the increase in the eligibility threshold limit from Rs.1 Cr. to Rs.5 Cr., inclusion of Service Tax assessees in the scheme and the reduced role of jurisdictional Commissionerates in respect of Large Taxpayers opting for the scheme.  It is thus recommended to create 23 exclusive Service Tax Commissionerates, i.e., 17 additional Commissionerates, primarily on the basis of certain criteria:  It is also recommended to provide 14 Commissioner (Appeals) primarily on the basis of 1 Commissioner (Appeals) for every 2 executive Commissioners, plus at locations with heavy pendency.  Three Chief Commissioners, together with the necessary complement of staff are required to provide leadership and cohesion and also monitor performance in major tax-paying centres i.e. 2 at Mumbai and 1 at Delhi. For other locations Chief Commissioners may also be considered for the combined jurisdiction of Service Tax and Central Excise.  The total staff requirements for managing nearly 75% of the Service Tax target of Rs 65,000 cr in 2009-10 and assessee base of about 3,85,000 out of 7,00,000 as on March 31, 2010 through 23 exclusive Service Tax Commissionerates is 8,789 personnel or 7,354 personnel after accounting for the existing sanction . This compares extremely favorably with the manpower deployed for collecting any other tax, direct or indirect, by a huge margin.  As regards Customs Commissionerate, falling under the categories of Exclusive Import (Sea), Exclusive Export (Sea), Exclusive Import (Air), Exclusive Export (Air), Composite Commissionerate, Airport Commissionerate and Commissionerate (General). As regards Preventive Commissionerates, they vary so much in the geographical dispersion and field units, the Group has largely gone by the recommendations made by the respective Preventive Commissionerates, while making the recommendation for their strengthening  Group has proposed for creation of 14 new Customs Commissionerates, including two Preventive Commissionerates.  Creation of two posts of Commissioner (Adjudication),one at JNCH and another at Chennai  Creation of four new Customs (Zones) at Hyderabad, Chennai, Bangalore and Ahmedabad  Augmentaion of existing preventive Commissionerates at Amritsar, Jodhpur, Mumbai, Kolkata, Patna and Lucknow  Creation of posts of Principal Chief Commissioners at Delhi, Mumbai, Chennai, kolkatta, Principal Chief Commissioner Audit/Compliance and also upgrading certain posts to PCC like DGRI, DGCEI, DG (Audit), DG (NACEN), DG (System), DG (ST), DG(Inspection) and DG (HRD).  Complete re-organisation of Audit set-up in CBEC has been recommended, by shifting from existingtransaction based PCA, at Custom Houses to record base audit and Common audit/compliance verification Commissionerates for Customs, Excise and Service Tax. The proposal is to create 10 new Zones and 40 new Commissionerates. In this context, manpower requirements have been projected keeping in view that a significant number of staff requirements could be met with by diverting staff from existing formations.  Creation of six exclusive Single Window Commissonerates for SEZs/EOUs/STPs  Recommendations for strengthening of (a) Directorate General of Valuation; (b) Commissioner (Appeal)’s office-and revising the norms for disposal of cases by Commissioner; (c) CDR’s office; (d) Directorate of Legal Affairs.  Overall implications of the recommendations made by the Group, as regards the manpower requirements have been worked out. In sum, a total of 18,067 additional posts will be created. Out of this, 989 posts will be for Group ‘A’ officials such as Chief Commissioner, Commissioner and Assistant Commissioners. The remaining will be for Group B, C and other category consisting of Superintendents, Inspectors, Havaldars and field staffs. Currently, the sanctioned strength of CBEC is 66,808. Change Process - Dialogue THe CBEC had dialoge with the stake holders namelsy the trade and the staff unions and the proposal was sent for expenditure clearance in 2010. It was deliberated with the Expendidire depoartment of Government of India. The final porosal was sent for Departmentment of Personnel and Training in 2013. After several discussions, the re-structuring proposal was approved by the Union Cabinet in May 2014 . Change Process- Do The CBEC notified the field formations under re-structuring and re-organisation of filed formations and allocated various revised strength at all levels to all the filed formationsOn 01.08.2014. As per final cadre re-structuring and reorganisation, 18,067 additional posts were created including 2,118 temporary posts for five years. This enabled uniform promotion opportunity for all the cadres of the CBEC that has beeb stagnated for several years. Although, creation of additional posts will involved an expenditure of approximately Rs 774 crore, it would help in collecting around Rs 68,000 crore annually.The new formations were started functioning from 15.10.2014. Accordingly, the number of formations were re-organised as below: No. of Central Excise Zones 23 No. of Central Excise Ciommissionerates 119 No. of Service tax Zone 04 No. of Service Tax Commissionerates 22 No. of Customs Zone 11 No. of Customs/ Customs (P) Zones 60 No. of Appeal Commissionerates 60 No. of Audit Commissionerates 45 Large Tax Units 08 Directorate General / Directorates 20 Change Process - Evaluate To elicit the feedback from the officers of the department, a pilot survey was conducted by designing a small questionnaire in google forms and circulating intamon the officers of the department. The form of thequestionaire is given in Appendix…..the results of the questionnaire is summarised as below.  The process took unduly long time. The process was initiate in 2008 and it took seven years for the new structure to come into being. The need assement done in 2008 and 2009 are of no meaning in 2015. Even after seven years many issues such as stagnations, inadequate infrastructure are yet to be addressed.  When Government t keen on to introduce GST from April, 2016 onwards, Cadre Restructure has not merged Central Excise & Service Tax work  Distribution of posts and formation of new formations was done with metros only in mind. In other ares the service tax and central excise work was kept intact while the staff strength was reduced by almost half , resulting in hardship to staff.  Staff allocation in CR is not as per work load prevails. From previous CR, work load was increased in the last 12 year, but staff allocation reduced in some commissionerate without any reason.  Now, after creating offices at places (read metros) that do not require expansion and reducing staff strength at non-metros, work and assessees and staff are the sufferers. For example. DGST office in Chennai is yet to start function. But ranges of Coimbatore having assessees of central Excise and Service Tax are crying for staff strength.  The most stagnated posts in the department were in the grade of Inspectors/Superintendents but it is unfortunate that the posts have not been properly distributed to mitigate the specific problem, instead it has created a lot of additional posts in the top echelon which is not helping the Department any useful manner. By downsizing the posts in the lower cadre, it has created an imbalance in the working system. It also does not seem to improve the working conditions by putting additional burden on the existing staff.  It took me nearly 19 years to get my first promotion as Superintendent. But in the cadre restructuring, Inspectors, who have put in less than 13 years of service were promoted. Now everyone is treated as same.  Any cadre restructuring should remove stagnation in every cadre, especially, in the lower rungs.It is on record that many of the cadres in the lower rungs have not benefited much , especially in Tamil Nadu. Even those who had been promoted after cadre restructuring have suffered heavily due to transfers. Creation of Commissionerates/posts were not well balanced.  The purpose of the Cadre restructuring is to remove the stagnation, where as the present Cadre restructuring has not removed the stagnation in the cadre of inspectors working in Tamil Nadu  The stagnation position of Group B Gazetted and non-Gazetted officers were not redressed in a genuine manner. The more benefited officers are ministerial and Class I Officers. Group B cadre were neglected and their interest was not taken care of properly  The main way to improve tax payer services is through computers and with ACES system still not up to mark, cannot say how it has improved tax payer services  All the day to day work in Central Excise, Customs and Service Tax must be online and responsibility should be fixed individually.  Revenue should not be the criteria; Correct distribution of work force.  Before GST, a suitable cadre restructing should take place, otherwise the department will suffer as it had during the initial period when Service tax was introduced.  Infrastructure management was not done properly. There are deficiencies in physical as well as IT infrastructure in the many of the newly formed commissionerates and Divisions. Conclusion Change is an ongoing and never-ending part of organisational life and leading successful change is incredibly difficult. The change process is not a linear stage-by-stage process but an interconnecting cycle of activity that merges the beginning, middle and end of each process step. During the change process, agencies may face obstacles to change. Such obstacles should be assessed and handled as risks to the overall change effort. With most structural change, both positions and people are affected. Managing successful change in the government is a challenging pursuit. Successful change is possible when the principles are applied appropriately, the process followed flexibly, and barriers recognised and considered suitably. Finally, the principles, process and barriers need to be applied within the context of the extent and scale of the change and adapted to suit the specific culture of the agency. In 2014, India has been ranked 152 out of 185 countries on ease of “paying taxes” in the World Bank’s “Doing Business” indicators. This is a stark indication of the gap between where we are and where we ought to be. The big question is how the tax administration can be transformed to radically improve the ranking if India is to emerge even among the top 50, with a view to improving its ranking steadily thereafter. To answer this question, we need to assess ourselves against global best practices. Against this backdrop, the CBEC underwent a major structural change recently. Dynamic external environment and internal needs led to the changes in the task, processes, structure and competencies within the organization. Still in the perception of the other stake holders, CBEC has to go a long way to adapt to the rapid changes that are happening around the world in economic, cultural, social and technological spheres and adopt best practices. We can look at this in two ways. Firstly, though in the recent past a lot of changes happened in the tax policy and procedure towards simplification of tax structure and compliance system, they are not happening at the speed atwhich the world is changing. Secondly, we have not invested in the perception management system as is done by some of the developed countries like the United Kingdom, Australia etc. In either case, the finger points towards us only and as the members of the organization we need to ask ourselves the following questions- Who and what we are? What is our purpose? Whom do we serve? Churning these questions, may make the cadre restructuring more meaningful. As we are heralding in GST regime, finding answers to these questions in a purposeful manner, will certainly place our organization the top of the pubic organizations but also put in top rankers in the ease of doing business and make the ‘make in India campaign much more meaningful.


Bibliography 1. CBEC. (2010). Proposal for Cadre Restructuring/Reorganisation of field formations of CBEC. Central Board of Excise and Customs, Department of Revenue, Ministry of Finance, GOvernment of India. 2. Cliffs Notes. (n.d.). Retrieved July 8, 2015, from http://www.cliffsnotes.com/more-subjects/principles-ofmanagement/managing-change/opposition-to-organizational-changes 3. Creasy, T. (2007). Defining Change Management. Retrieved June 2015, from Change Management.com: http://www.changemanagement.com/Prosci-Defining-Change-Management.pdf 4. Felkins, K. P., Cakiris, B. J., & Chakiris, K. N. (1993). Change Management: A Model for Effective Organisational Performance. New York, US: Quality Resources. 5. OECD. (2013). Comparative information on Tax Adminstration in OECD countries and other Emerging Economis. Retrieved July 5, 2015, from Keepeek.com: http://www.keepeek.com/Digital-AssetManagement/oecd/taxation/tax-administration-2013_9789264200814- en#page39 6. Paton, R. A., & McCalman, J. (2013). Change Management: A Guide to Effective Implementation. New Delhi, India: Sage Publications. 7. Study Group I. (2010). Report of the Study Group on Restructuring of the formations unde CBEC. Central Board of Excise and Customs. 8. Study Group II. (2010). Report on Restructuring of Customs Formations under CBEC. CBEC. 9. TARC. (2014). First report of the Tax Administration Reforms Commission. Government of India, New Delhi. 10. Workforce performance Directrate. (2015). Structural Change Management: A Guide to Assist Agencies to Manage Change. Retrieved July 7, 2015, from Public Sector Commission: https://publicsector.wa.gov.au/document/structural-changemanagement-guide-assist-agencies-manage-change

Promotion prospects are a vital factor affecting the morale and efficiency of the service personnel and hence the effectiveness of the cadre in discharging the role assigned to it. This aspect will, therefore, have to be kept in view while formulating proposals for restructuring a cadre. The Cadre Authority will do well, therefore, to keep under constant observation the trends of promotion/stagnation in the cadre. Constant updating of grade-wise seniority lists helps in correctly assessing promotion trends and prospects. Such updating may be carried out at least once in year i.e. as on first of each calender year. An assessment may be made of the anticipated promotion prospects (as a result of cadre review) vis-a-vis existing (past) promotion trends. A realistic estimate of likely vacancies in each grade for the next three years, drawing up a programme of DPC meetings at regular intervals and strict adherence to planned recruitment programme will reduce the chances of occurance of artificial bottlenecks and infuse in the minds of the Service personnel a sense of confidence in their future.

CADRE REVIEW OF CENTRAL SERVICES
GROUP `A' - DETAILED GUIDELINES
INTRODUCTION
The Administrative Reforms Commission which examined the existing machinery for the management of different All-India and Central Services Cadres, had in their Report on Personnel Administration made the following recommendations:-
a) For all Services advance projections should be made of the requirements of personnel for five years at a time. Mid-term appraisal also should be made if circumstances warrant it and necessary correvtives made on the basis of the apprisal.
b) Such projections should be made by cadre management committees which should be constituted in the manner described..........
2. The Government of India accepted the above recommendations with modifications that cadre review should be made every three years instead of every five years and that while the user interests need not be associated with the review committees, their requirements may be taken into consideration while making the reviews. It was also laid down that the composition of the Cadre Review Committee would be as follows:-
i) Cabinet Secretary - Chairman
ii) Secretary, Ministry of - Member
Finance, Deptt. of
Expenditure
iii) Secretary, Deptt. of - Member
Personnel & Training
iv) Secretary of the - Member
Ministry controlling
the cadre

At later stages, the Defence Secretary and the senior most member of the cadre under review were also included as members in the Cadre Review Committee.
3. The Department of Personnel & A.R., after studying details of various measures taken by the cadre authorities towards scientific management of their cadres, formulated certain broad guidelines for objective cadre management and circulated the same to all concerned Departments, vide O.M.No.5/1/71-PP(Vol.VI) dated the 6th May,1972,with the request that they set up Cadre Review Committees in the manner prescribed and arrange to have the cadre structures reviewed on a priority basis. This was followed up in March,1973 by an `Approach-Note' on cadre review delineating the various aspects to be considered while preparing proposals for cadre strength reviews.
4. The Third Pay Commission recommended the creation of a standing `Body on Pay and Cadre Management' to be headed by a serving or retired Judge of the Supreme Court or a High Court and having four non-functional members with experience of problems connected with Pay determination job-evaluation, personnel management and other allied matters. While this specific recommendation was not accepted by the Government, it was nonetheless decided that:-
a) A unit may be set up, if necessary, in due course in the Ministry of Finance for dealing with cases of limited pay revisions. In the meanwhile, cases which may arise relating to job evaluation or revision of pay scale of any particular category (Including creation of a new pay scale where necessary) may be dealt with in that Ministry according to normal procedure; and
b) The Department of Personnel & A.R., who are dealing at present with matters relating to cadre management of the all-India and Central Class-I services may also set up a unit, if necessary,indue course for advising theMinistries/Departments of cadre management of various services in Class-II and III as well.

Role of the Department of Personnel & A.R.
5. The Department of Personnel & A.R. is closely associated with work relating to cadre review of various Services. The Department issues guidelines regarding policy and methodology of cadre reviews, examines the proposals prepared by the concerned cadre controlling authority and prepares an analytical brief containing the views of the Department of Personnel & A.R. for the use of members of the Review Committee. The Department maintains liasion with the cadre authorities and provides guidance and expertise in the formulation of proposals for periodic reviews of cadre strength. Recently, it has been decided that the department should take more initiative in regard to the cadre reviews instead of leaving it with the concerned Ministries.
Need for re-orientation of the review process.
6. The overall approach to cadre strength review has recently been re-examined in the Department of Personnel & A.R. in the light of experience gained so far. It has been observed that despite circulation of broad guidelines and the Approach Note (referred to in the earlier paragraphs), the cadre review proposals prepared by the Departments continue to suffer from a number of deficiencies. In particular, the following considertations which are pertinent in determining cadre strength of various Services do not seem to have received adequate attention of cadre authorities:-
a) projection of manpower requirements on scentific lines;
b) utilisation of cadre posts and deployment of cadre officers;
c) objective assessment of future promotion prospects;
d) rationalisation of cadre structure;
e) the level(s) at which various reserves are to be created, their quantum and utilisation and
f) formulation of a realistic recruitment plan.
Keeping in view the above mentioned factors and the comments of various departments, a revised comprehensive set of guidelines has now been drawn up on the subject. The new guidelines which are elaborated in the ensuing sections should facilitate framing of proposals for triennial reviews of cadres with a full understanding of the principles involved. A set of format which may be used in this regard is appended (Appendix).

DETAILED GUIDELINES FOR THE FORMULATION
OF CADRE STRUCTURE REVIEW PROPOSALS.

Objectives
7. The basic objectives of periodical review of a cadre are as follow:-
a) To make advance projections of requirements of personnel for the next three years and to plan recruitment programme on a scientific basis; and
b) To bring about rationalisation of cadre structure with a view to improving the efficiency and morale and enhancing the effectiveness of the Service.
Need for advance planning of personnel requirements:
8. The need for advance planning of the requirements of personnel is to be stressed for following reasons:-
a) Timely recruitment of personnel in adequate numbers is essential to prepare them for future deployment.
b) The process of getting the new posts sanctioned is time consuming.
c) In the absence of advance planning of manpower requirements, there may be violent fluctuations from time to time in the rate or recruitment with obvious adverse effects on the quality of recruits and cadre management.
Rationalising cadre structure
9. The cadre structure of a Service should satisfy the following criteria:-
a) Different grades of the Service should reflect distinctly different levels of duties and responsibilities;
b) Structure of the cadre should be such as to facilitate smooth movement of personnel, both vertical as well as horizontal; and
c) It should promote maximum efficiency commensurate with economy expenditure.
Cadre Strength
10. Basic constitutents of a Central Group `A' Service(cadre) should normally be:-
a) Regular duty posts;
b) Probationers reserves; and
c) Other reserves, viz.
i) Leave Reserve
ii) Training Reserve; and
iii) Deputation Reserve.
The sum total of (a) to (c) would represent what may be called the authorised strength of the cadre of Service. These terms are explained in the following paragraphs:-
Regular Duty Posts:
11. Regular duty posts are those posts in the cadre which carry the functions that fulfil the objectives for which the Service was constituted.
Probationers Reserve
12. Direct recruits are normally given initial training for periods ranging from one year to three years while on probation. The posts against which they are shown during the training period, which includes post-entry institutional as well as on-job training should not be included in the strength of regular duty posts, but should be shown separately as probationers reserve. In case such reserve already forms part of junior duty posts or other reserves, necessary adjustment will have to be made to show it as a separate reserve. If the period of training of a probationer is one year, the size of probationers reserve should be equal to the size of one batch of direct recruits; if the period of training is 2 years, the reserve has to be double the size of a batch; and so on. Where the size of recruitment varies from year to year, the maximum recruitment in one year during the period of review may be taken as the basis for determination of size of reserve.
Other Reserve
13. `Other' reserves comprise leave, training and deputation reserves. There is an important difference between the probationers reserve and `other' reserves. The former is set apart for a definite category of service personnel. viz. fresh recruits directly appointed to the lowest rung of the Service. The latter serve a more general purpose of providing substitutes against vacancies caused due to Service officers proceeding on long leave, training or deputation. For every officer shown against other reserves, there should thus be one officer on leave, training or deputation. Those reserves are needed in order to ensure that the regular duty posts are continuously manned by competent officers and are ordinarily created in the entry grade of the Service. Broad guideline for arriving at the appropriate size of various reserves are given below:-
Leave Reserve
14. Actual utilisation of leave by officers (for at least 45 days at a time) and the utilisation of the existing leave reserve (if any) by the Department during the preceding 3 to 5 years should normally determine the size of leave reserve. In addition, the practicability of filling up of leave vacancies, especially where the duty posts are widely scattered over field formations, may also be examined while determining desired size of the leave reserve.
Training
15. The imperative need for imparting on the job refresher/ professional training periodically to the personnel at various levels of the Service in order to equip them to meet the growing challenges of developmental administration can hardly be over-emphasised. For this purpose, a training reserve of an appropriate size will have to be provided for the cadre structure. The size is to be worked out on the basis of past experience (of, say, the last 5 years) and a well drawn-out programme for training of officers over the next 3 years.
Deputation Reserve
16. Officers of organised Service are in constant demand for manning posts on deputations in the Secretariat and other Headquarter Organisations, Public Sector undertakings etc. Spells of deputation to such ex-cadre posts afford the officers an opportunity to apply and test their knowledge, skills and talents in new fields and situations. Deputation also helps in imparting fresh outlook to their work on return to their organisation. However, while sending officers on deputation, it should be ensured that the essential needs of the service are not sacrificed, nor does it give rise to distortions in the recruitment programme or to other cadre management problems. As regards the size of the deputation reserve, it may be fixed in the light of past experience and the estimated minimum number of officers likely to be away on deputation during the next three years. Once the size of deputation reserve is fixed, a conscious effort should be made to see that there is neither over-utilisation nor under-utilisation so as to avoid problems in the smooth management of the cadre.
Encadrement of ex-cadre posts
17. Often departments create for various reasons, a number of posts having more or less similar functional duties and responsibilities as the cadre posts. Such posts are manned by both cadre officers and those outside the cadre (s). It should be the constant endeavour of cadre authorities to periodically review the position regarding such posts with a view to encadre them keeping in view:-
(a) the nature of functions and responsibilities attached to them;
(b) the likelihood of their continuing; and
(c) the desirability of deploying cadre officers to such posts.
Recruitment Planning
18. Rate of recruitment to a cadre is essentially a function of the maintenance and growth needs of the Service. A third important factor that determine recruitment size is the quantum of `gaps', i.e. the number of vacancies remaining unfilled for a period of one year or more. It would be convenient to discuss recruitment plan under the three main heads representing the three basic components, viz. (1) maintenance needs (ii) growth needs and (iii) gaps. While drawing up the recruitment plan, promotion prospects will also have to kept in view.
Estimation of maintenance needs
19. Maintenance needs arise out of wastage-both normal (due to retirments on superannuation) and abnormal (due to resignations) deaths, dismissals, etc.), Data on the future wastage pattern for say 5 years should be compiled both in respect of direct recruits and promotee officers. In particular some Group `B' officers likely to be promoted to the Service during the next three years may be retiring within the period of review. To smooth out violent annual fluctuations, if any, an average of the next 5 years should be taken to represent the maintenance requirements of the Service/cadre on account of normal retirement. As regards abnormal wastage to resignation, dismissals, deaths, etc., this may be estimated on the basis of actual experience during the past five years.
Estimation of growth needs
20. Each cadre controlling authority should have a reasonable estimate of the future growth rate of personnel say, over the next 5 years. The actual retirements for the next three years (i.e. the period of the triennial review) will have to be worked out as possible. In general, the growth needs of a service will have to be assessed under the following components:-
(a) Normal growth of work in the current functional fields;
(b) New functions/schemes likely to be undertaken
(c) Policy-induced changes relating to:-
i) Organisation/Structure;
ii) Personnel Policy; and
iii) Administrative/procedural reforms.
21. Rate of increase in work load within the existing functions of the service may be studied with reference to past trends and projected progress of on-going schemes/programmes during the next three to five years. Normal growth in work should not generally lead to any significant increase in number of posts unless it can be demonstrated on the basis of quantitative norms that increase in work has a direct bearing on staff strength.
22. Along with progress of on-going schemes, some of which may taper off during the next few years and thereby reduce the requirement of staff on them, a careful study should be made of new programmes/ projects and activities likely to be taken up during the next years. Necessary correlation between financial and physical targets and staff requirements should be established.
23. Policy changes in the personnel field also have an impact on future growth of personnel. Some policy decisions may have been taken or likely to be taken which will have an important bearing on the functions, organisation and structure of the Department/Service. Likely impact of all such changes on the cadre strength should be carefully assessed.
24. A note of caution may be sounded here. The projection of future requirements is not necessarily an extrapolation of past trends for the simple reason that the past conditions might not hold good in the future. Policy changes recently introduced or likely to be introduced often influence the future behaviour pattern of the trend which may not be amenable to quantification. Nevertheless, backed by enlightened judgement and past experience, the cadre authority should still be in a position to assess the growth rate within a reasonable narrow margin or error.
Under Recruitment resulting `gap'
25. A `gap' may be defined as the size of regular vacancies in the cadre persisting continuously for more than a recruitment year, even though such vacancies migth have been filled by ad-hoc appointments. Regular vacancies are long-term vacancies which are required to be filled on a regular basis in accordance with the Recruitment Rules. The main causes of the gaps which usually accumulate in the lowest rung of the service are:-
a) Non-availability of suitable candidates;
b) Deliberate under-recruitment so as to avoid promotion blocks at a later stage or for other reasons; and
c) Defects in recruitment planning, such as failure to make proper allowance for abnormal wastage, delays etc.
A careful examination of the causes should be made so as to arrive at a reasonable figure by which the gap should be reduced and recruitment increased over the next three years.
Adverse effects of over or under recruitment.
26. Under recruitment and ad-hoc appoitments should be avoided as far as possible, as these will create distortions in the cadre. In any case, it should be ensured that ad-hoc appointments do not persist for more than a year at the most. Where ad-hoc appointments are sizeable and have been continuing for long periods creating problems for the Cadre Authority and adversely affecting the morale of officers concerned, bold measures may have to be thought of, say in the directions of a radical restructuring of the cadre, a reassessment of promotion quotas and review of recruitment rules.
Over recruitment is as harmful, if not more, as under recruitment. The former leads to future blockades in promotions. The scope of undoing the damages done by past over-recruitment is very limited. The first objective of recruitment planning should, therefore, be to ensure that recruitment is made regularly every year and the rate of annual intake by direct recruitment and promotion from Group `B' is kept within a fixed optimum rate. A study carried out by the Cadre Review Division has indicated that the optimum rate of annual intake should be 3% of the authorised cadre strength.
If a cadre is suffering from gross under recruitments in the past, the aforesaid optimum rate may fall short of the number required to fill the big gap in the cadre. A sepcial method should be adopted on a one-time basis to ensure that gap is filled without creating future blockades in promotion. An appropriate method would be to hold a limited departmental competitive examination of the eligible Group `B' officers for filling the gap by promotion.
Promotion Trends
27. Promotion prospects are a vital factor affecting the morale and efficiency of the service personnel and hence the effectiveness of the cadre in discharging the role assigned to it. This aspect will, therefore, have to be kept in view while formulating proposals for restructuring a cadre. The Cadre Authority will do well, therefore, to keep under constant observation the trends of promotion/stagnation in the cadre. Constant updating of grade-wise seniority lists helps in correctly assessing promotion trends and prospects. Such updating may be carried out at least once in year i.e. as on first of each calender year. An assessment may be made of the anticipated promotion prospects (as a result of cadre review) vis-a-vis existing (past) promotion trends. A realistic estimate of likely vacancies in each grade for the next three years, drawing up a programme of DPC meetings at regular intervals and strict adherence to planned recruitment programme will reduce the chances of occurance of artificial bottlenecks and infuse in the minds of the Service personnel a sense of confidence in their future.
Recruitment Plan
28. The sum total of maintenance needs and growth needs (including increase in reserve needs) will indicate that total recruitment size for the next three years. To this should be added a part of the gap which is proposed to be made good during the period of review. If one third of the total thus arrived at exceeds 3% of the authorised cadre strength, annual intake should be restricted to 3% only.
`Creation of posts not envisaged by the Cadre Review Committee'.
29. Normally additions to a cadre by way of increasing the number of posts at different levels should be considered only in the course of a triennial cadre review. Mid-review changes should be avoided as far as possible. Regular cadre reviews carried out at triennial intervals must envisage such eventualities while making advance projections for the three year period of additional man-power requirements. Accordingly the need for creating post not envisaged by the Cadre Review Committee before the next cadre is due, can be expected to be rare. In the event, however, of such an eventuality it may be ensured that the additional posts so created conform to the cadre structure most recently approved by Cadre Review Committee. There can, however be no rigidity in this regard. In any case the cadre authority should consult P.P. Division* of the D.P. & A.R. in this regard.
Review By S.I.U.
30. As per the current practice followed by Ministries/Departments no cadre review is initiated in respect of any Service/Cadre which is likely to be effected by the recommendations of a current SIU study of an organisation under a Ministry/Department. The review proposals are required to be drawn up only after the SIU report has been acted upon by the Department concerned. In case, however, SIU happens to undertake a review of an organisation under a Ministry/Department soon after a cadre or cadres controlled by it have been restructured on the recommendations of the Cadre Review Committee, the Department may ensure that SIU finalises its report in consultation with C.R. Division of Department of Personnel & Training in so far as its recommendations may affect the cadre structure/strength of the concerned service(s).
Reference to Ministry of Finance
31. In so far as the cadre review proposals involve only structural changes in the cadre there is no need for prior clearance by the Ministry of Finance. Where, however, cadre review proposals involve introduction of new pay scales and/or changes/adjustment in the pay scales by way of say merger, bifurcation etc., it is desirable to obtain the crearance of the Department of Expenditure before incorporating such changes/adjustments in the cadre review proposals being formulated by the concerned cadre authority.
Presentation of Cadre Review Proposals

32. While considerable latitude will be available to the cadre authorities in preparing and presenting cadre review proposals, it must be ensured that the necessary statistical data are compiled and updated on a continuing basis in the Format given in Appendix. It is also necessary while presenting review proposals to give a sketch of the historical background of the Service, its objectives and the functional and organisational structure of the Cadre/Service, special features peculiar to the Service and difficulties and problems faced during the process of cadre management. Present as well as the proposed organisational structure of the Department and the service showing posts at different levels with their designations, pay scales and the functional inter-relationship among them along with organisational chart should be enclosed with the cadre review proposals. The posts to be upgraded should be identified and the justifications for upgradation should be mentioned. Recruitment Rules, as amended till to date, both respect of Service posts as well as its feeder posts, grade-wise seniority lists updated as on first of the`Current Year'(i.e. Year in which the proposals are being framed) should invariably be attached with the proposal papers. Financial implications of the cadre review proposals should also be indicated. In the Format the reference year may be taken as beginning from first January of the current year. For convenience, however, in the Format attached to these Guidelines, `current year' has been taken as 1992. The other years (preceding/succeding 1992) mentioned in different forms will correspondingly change according to the `current year'.

Transfer Policy,--- Reversion to old pension scheme -----Somvir Rana & ors vs. Govt of NCT of Delhi & anr.

Transfer Policy

Transfer Policy
In terms of instructions issued by Department of Personnel & Training (DoPT) on transfer/posting of Government employees, all Ministries/Departments of Government of India are required to have their own guidelines for transfer/posting of their employees providing for the following -
  1. minimum tenure;
  2. have a mechanism akin to Civil Services Board for recommending transfer; and
 Respective Ministries/Departments are also required to place the transfer policy in public domain.

There is no proposal to formulate single transfer policy for the Government employees as guidelines for transfer/posting of employees depend on the specific requirement of individual Ministries/ Departments. Moreover, the State Public Services are under State List for which the State Governments are competent to make rules and policies. Accordingly, there is no proposal to constitute any commission for single transfer policy for both Central & State employees.

This information was provided by the Union Minister of State (Independent Charge) Development of North-Eastern Region (DoNER), MoS PMO, Personnel, Public Grievances & Pensions, Atomic Energy and Space, Dr Jitendra Singh in written reply to a question in Lok Sabha today.


Reversion to old pension scheme : The Special case of administrative delay can not be generalized for all


Press Information Bureau 
Government of India
Ministry of Personnel, Public Grievances & Pensions

19-July-2018 16:25 IST

Reversion to old pension scheme 

In accordance with the scheme for National Pension System (NPS), as notified vide Ministry of Finance (Department of Economic Affairs)’s Notification No. 5/7/2003-ECB & PR dated 22.12.2003, the System is mandatory for all new recruits to the Central Government service (except armed forces) from 01.01.2004.  Accordingly, as per Rule 2 of the Central Civil Services (Pension) Rules, 1972, as amended on 30.12.2003, these rules are applicable to Government servants appointed to civil posts on or before 31.12.2003. The date on which the vacancies arose or the date on which the examination was conducted for filling up the vacancies is not relevant for deciding the applicability of the Central Civil Services (Pension) rules, 1972.

Ministry of Home Affairs have not sought any advice from Department of Pension and Pensioners’ Welfare on the question of having a policy to cover the paramilitary personnel appointed after 01.01.2004 under the Old Pension Scheme on the ground that the vacancies arose, or the examination was conducted, in the year 2003. However, a reference was received from Ministry of Home Affairs in a specific case relating to appointments as Sub-Inspector in various Central Para Military Forces after selection in August, 2003 on the basis of an Examination conducted in 2002. Appointments on the basis of these selections were made in Central Reserve Police Force in 2003 and the candidates appointed were covered by the pension scheme under Central Civil Service (Pension) Rules, 1972. However, in the Border Security Force, offers of appointment on the basis of the same examination / selection were issued in January, 2004. On a petition filed by some personnel appointed in the Border Security Force on the basis of that examination, Hon’ble High Court of Delhi directed to cover the petitioners under the Central Civil Service (Pension) Rules, 1972 on the grounds of administrative delay on the part of Border Security Force in making appointments. The order of Hon’ble High Court of Delhi was implemented by the Ministry of Home Affairs/Border Security Force in view of the peculiar circumstances of that case. The decision taken in that case is, however, not relevant for deciding applicability of Central Civil Service (Pension) Rules to all appointments made on or after 01.01.2004 in the Central Para Military Forces or in any other Department / organization on the basis of year of examination / selection.

This information was provided by the Union Minister of State (Independent Charge) Development of North-Eastern Region (DoNER), MoS PMO, Personnel, Public Grievances & Pensions, Atomic Energy and Space, DrJitendra Singh in written reply to a question in Rajya Sabha today.


Somvir Rana & ors vs. Govt of NCT of Delhi & anr.